Updated weekly · 17 Nov 2026
The AI build-out
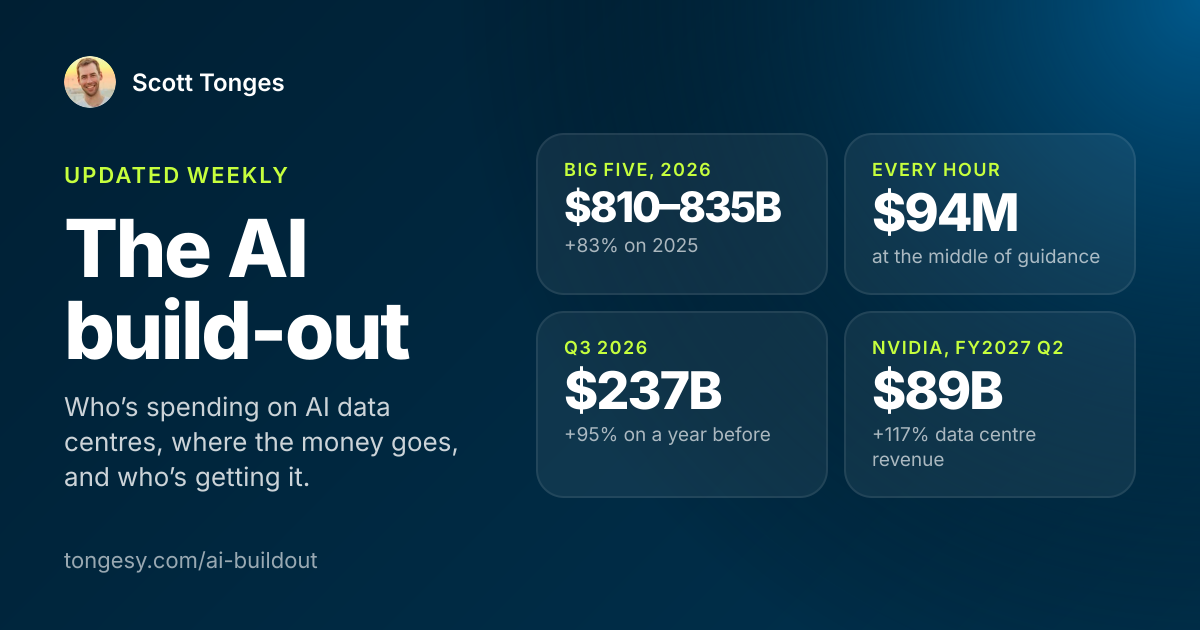
This year Microsoft, Alphabet, Amazon, Meta and Oracle expect to spend about $810–835B on data centres, chips and the power to run them. That's roughly $94 million an hour, day and night. Here's where that money goes, who's getting it, the deals that send it round in circles, and the companies I'm watching.
- Big five, 2026
- $810–835B
- 83% more than 2025's $449B
- Every hour
- $94M
- at the middle of 2026's guidance
- Q3 2026
- $237B
- +95% on a year before
- Nvidia data centre, FY2027 Q2
- $89B
- +117% on a year before
For scale
One year of it, beside some of the biggest projects in history, in today's dollars.
- The big five's AI build-out, 2026 alone$823B
- Interstate Highway System (35 years)$634B
- Oil and gas exploration and production worldwide, one year$570B
- Apollo program (1960–73)$309B
- Marshall Plan (1948–52)$137B
- International Space Station$110B
- Manhattan Project$28B
The spending race
Capital spending by quarter, in US dollars: mostly servers, chips, data centre buildings and the land and power under them. Hover a quarter for the split.
- Microsoft
- Alphabet
- Amazon
- Meta
- Oracle
By year
Calendar years. This year's bar runs from what they've spent so far to what they've told investors they'll spend.
- 2023$161B
- 2024$261B
- 2025$449B
- 2026$810–835B $575B so far
- Microsoft$170B Calendar 2026
Said on the fiscal Q1 2027 call, down from about $175B because some third-party capacity deliveries were delayed. CFO Amy Hood expects fiscal Q2 (Oct–Dec 2026) capex above $50B. Sources disagree on the year: CNBC said the $170B covers calendar 2027, while call summaries say it is the current calenda Microsoft expects capex to speed up in the second half of fiscal 2027 (January to June 2027), mainly on CPUs, GPUs, memory, storage and delayed third-party capacity, and expects to stay free-cash-flow positive in fiscal 2027.
Said 28 Oct 2026 · source · Capex = capital expenditures including finance leases, as Microsoft reports them.
- Alphabet$195–205B 2026
Raised twice this year, from $175–185B in February. Alphabet said it still expects capex to rise significantly in 2027 and will give more detail on its Q4 call.
Said 22 Jul 2026 · source · Capex = purchases of property and equipment.
- Amazon$220B 2026
About $220B, up from about $200B, partly because memory costs more. It says it won't have enough capacity this year or next. Amazon said it expects to spend meaningfully more in 2027, mostly on AWS.
Said 30 Jul 2026 · source · Capex = purchases of property and equipment, before proceeds and incentives (so higher than the cash capex Amazon quotes).
- Meta$135–145B Full-year 2026
Range narrowed by raising the low end from the previous $130–145B. Capex includes principal payments on finance leases. On its Q3 2026 call, Meta said it is still building its 2027 budget and capacity plan, will give more detailed guidance later, and intends to keep funding attractive AI and core-business projects.
Said 21 Oct 2026 · source · Capex = capital expenditures including principal payments on finance leases, as Meta reports them.
- Oracle$90–95B FY2027 (Jun 2026 – May 2027)
$90–95B before customers pay back about $20–25B of it; no more than about $70B net.
Said 10 Sep 2026 · source · Capex = capital expenditures.
What forecasters expect
- $720 billion to $740 billion404K Research: Combined full-year 2026 capex guidance from Meta, Alphabet, Amazon and Microsoft 404kresearch.substack.com, 2 Nov 2026
- About $1 trillionAnalysts polled by FactSet (reported by CNBC): Combined 2027 capex of Meta, Alphabet, Microsoft and Amazon, with Alphabet projected to spend over $310B cnbc.com, 21 Oct 2026
- US$860 billion in 2026; nearly US$1.2 trillion in 2027Bank of America: Big Tech capex forecast, 2026 and 2027 (raised) 247wallst.com, 8 Oct 2026
- US$1.1 trillionWall Street consensus as cited by Goldman Sachs (via Yield Theory): 2027 capex for the five largest US hyperscalers, including Oracle yieldtheory.app, 4 Oct 2026
- about US$934.5 billionWall Street analyst consensus (compiled by Yield Theory): 2027 capex for Alphabet, Amazon, Microsoft and Meta combined, about 28% above their 2026 guidance of US$732.5 billion yieldtheory.app, 4 Oct 2026
- US$1.2 trillion in 2027 (group on pace for about US$800 billion in 2026)Goldman Sachs (team led by Ryan Hammond): Combined AI-related capex of the five biggest US hyperscalers (Amazon, Alphabet, Microsoft, Oracle, Meta), 2027, compared with a widely cited US$1.1 trillion consensus briefs.co, 27 Sep 2026
Spending against sales
Capex as a share of each company's revenue. The dashed line is 25%, about what a power utility spends, the classic capital-hungry business. Each chart has its own scale.
- Microsoft49%
from 15% in Q1 2023
60%25%Q1 202314.7% of revenueQ2 202319% of revenueQ3 202319.8% of revenueQ4 202318.5% of revenueQ1 202422.6% of revenueQ2 202429.4% of revenueQ3 202430.5% of revenueQ4 202432.5% of revenueQ1 202530.5% of revenueQ2 202531.7% of revenueQ3 202544.9% of revenueQ4 202546.1% of revenueQ1 202638.5% of revenueQ2 202645.6% of revenueQ3 202649% of revenue - Alphabet40%
from 9% in Q1 2023
60%25%Q1 20239% of revenueQ2 20239.2% of revenueQ3 202310.6% of revenueQ4 202312.7% of revenueQ1 202414.9% of revenueQ2 202415.6% of revenueQ3 202414.8% of revenueQ4 202414.8% of revenueQ1 202519.1% of revenueQ2 202523.2% of revenueQ3 202523.5% of revenueQ4 202524.5% of revenueQ1 202632.5% of revenueQ2 202637.5% of revenueQ3 202640.3% of revenue - Amazon38%
from 11% in Q1 2023
40%25%Q1 202311.1% of revenueQ2 20238.6% of revenueQ3 20238.7% of revenueQ4 20238.6% of revenueQ1 202410.4% of revenueQ2 202411.9% of revenueQ3 202414.2% of revenueQ4 202414.8% of revenueQ1 202516.1% of revenueQ2 202519.2% of revenueQ3 202519.5% of revenueQ4 202518.5% of revenueQ1 202624.4% of revenueQ2 202627% of revenueQ3 202638.3% of revenue - Meta54%
from 25% in Q1 2023
60%25%Q1 202324.8% of revenueQ2 202320% of revenueQ3 202319.9% of revenueQ4 202319.7% of revenueQ1 202418.4% of revenueQ2 202421.7% of revenueQ3 202422.7% of revenueQ4 202430.6% of revenueQ1 202532.4% of revenueQ2 202535.8% of revenueQ3 202537.9% of revenueQ4 202536.9% of revenueQ1 202635.2% of revenueQ2 202651.2% of revenueQ3 202654% of revenue - Oracle148%
from 21% in Q1 2023
160%25%Q1 202321% of revenueQ2 202313.8% of revenueQ3 202310.4% of revenueQ4 20238.5% of revenueQ1 202412.8% of revenueQ2 202419.6% of revenueQ3 202417.3% of revenueQ4 202428.4% of revenueQ1 202541.8% of revenueQ2 202557.2% of revenueQ3 202557% of revenueQ4 202574.5% of revenueQ1 2026108.1% of revenueQ2 202685.9% of revenueQ3 2026147.7% of revenue
Follow the money
2026's spending, from who's paying to what it buys. The split is a rough guide, from Bernstein's estimate of what a 1 GW site of Nvidia's newest chips costs in 2026 (about $47B); McKinsey's longer-run estimate is 60% chips and computers, 25% power and cooling, and 15% land and buildings.
- AI chips30% · about $247B
GPUs and custom accelerators. Nvidia makes most of them; Broadcom and Marvell design custom chips for Google, Amazon, Meta and OpenAI; TSMC makes nearly all of them, on machines from ASML.
- Nvidia
- Broadcom
- AMD
- Marvell
- TSMC
- ASML
- Memory and storage24% · about $197B
High-bandwidth memory stacked beside each chip, plus the DRAM and flash around it. Its share has grown as memory prices have soared.
- SK hynix
- Samsung
- Micron
- Sandisk
- Networking9% · about $74B
Switches, cables and optics that join thousands of chips into one machine.
- Nvidia
- Broadcom
- Arista
- Marvell
- Credo
- Lumentum
- Corning
- Rest of the rack5% · about $41B
CPUs, boards, in-rack power and cooling, and the assembly.
- Dell
- Celestica
- AMD
- Intel
- Buildings, power and cooling32% · about $263B
The shell, land, power plant, switchgear and cooling, and often new generation, which is where the delays are.
- Vertiv
- Schneider Electric
- Eaton
- GE Vernova
- Siemens Energy
- Bloom Energy
- Goodman Group
- CleanSpark
The biggest single winner
Nvidia's data centre revenue next to what the big five spend.
In Q1 2023 Nvidia's data centre sales were 11% of what the five spent on capex. By Q2 2026 they were 47%. Not all of it is the same money: Nvidia sells to other clouds, labs and governments too, and capex also pays for buildings, power and land.
- Microsoft, Alphabet, Amazon, Meta and Oracle: capex
- Nvidia: data centre revenue
The money loop
A lot of the money goes round in circles: chipmakers invest in AI labs, the labs sign huge contracts with clouds, and the clouds buy the chips. Each arrow points from who pays to who's paid. Hover a name to see only its deals.
- Buys compute or cloud
- Invests
- Lends or finances
Clockwise from the top right: AI labs, big clouds, GPU clouds and builders, chipmakers, investors and lenders. Deals of $5 billion or more. Headline values, often "up to" and spread over years. Dashed: changed since it was announced. Some of the biggest, like OpenAI's 6 GW of AMD chips, 10 GW of Broadcom chips and Meta's 6 GW of AMD chips, have no published value, so they aren't here.
Every deal
- $300BOpenAI → OracleBuys compute or cloudOpenAI agreed to buy about $300B of Oracle cloud compute over roughly five years from 2027, about 4.5 GW (Stargate). In March 2026 the two dropped a 600 MW expansion of the flagship Abilene, Texas site after financing talks failed; the main deal stands.Sep 2025 · changed · TechCrunch
- $250BOpenAI → MicrosoftBuys compute or cloudIn its for-profit restructuring, OpenAI committed to buy another $250B of Azure; Microsoft kept a 27% stake worth about $135B. Rewritten in April 2026: Azure is no longer exclusive and OpenAI's revenue share to Microsoft is capped, running to 2030.Oct 2025 · changed · Microsoft
- $138BOpenAI → AmazonBuys compute or cloudOpenAI signed a $38B, seven-year AWS deal in November 2025, then added $100B over eight years in February 2026, including about 2 GW of Amazon's Trainium chips.Nov 2025 · in progress · Amazon
- $121BAnthropic → SpaceXBuys compute or cloudUp to $120.5B of Nvidia GPU compute from SpaceX's AI unit (formerly xAI) through 2029, signed as a series of deals between May and October 2026; payments reach about $3.1B a month once all capacity is delivered, expected in December 2026 Anthropic's S-1 shows the commitment has grown from $45B to up to $120.5B; either side can cancel on 90 days' notice after early 2027May 2026 · changed · GeekWire
- $115BAnthropic → GoogleBuys compute or cloud$114.5B committed to Google TPU capacity through 2033 (several years), as disclosed in Anthropic's S-1 First disclosed in the IPO filing; this is separate from Google's equity investment in AnthropicOct 2026 · CNBC
- $110BAnthropic → AmazonBuys compute or cloudAt least $110B of AWS cloud services and Trainium chips through April 2036; non-cancellable except for a material breach by Amazon, and Anthropic pays Amazon the difference if its spending falls short The S-1 gives the minimum as $110B over 10 years, more than the $100B on fileApr 2026 · changed · CNBC
- $105BNvidia → SB EnergyLends or financesNvidia will back up to $105B of financing for SoftBank's SB Energy to build a 4.25 GW campus in Ohio, leased to OpenAI for 20 years, and invest $1.5B in SB Energy.Aug 2026 · CNBC
- $60BSoftBank → OpenAIInvestsSoftBank put $30B into OpenAI's 2025 round, then another $30B in 2026, much of it paid for with a record $40B bridge loan. The last tranche was paid on 1 October 2026; SoftBank owns about 13%.Mar 2025 · in progress · SoftBank
- $50BAmazon → OpenAIInvestsAmazon agreed to invest $50B in OpenAI: $15B up front and $35B once conditions were met. Fully paid by mid-2026, according to Amazon's filings.Feb 2026 · Amazon
- $50BAnthropic → FluidstackBuys compute or cloudAnthropic said it would put $50B into its own US data centres, built with Fluidstack in Texas and New York.Nov 2025 · in progress · Anthropic
- $45BAnthropic → MicrosoftBuys compute or cloudAt least $44.9B of Azure cloud spending from November 2026 to May 2033, payable regardless of actual usage The S-1 puts the minimum commitment at $44.9B, up from the $30B on fileNov 2025 · changed · GeekWire
- $45BAnthropic → NscaleBuys compute or cloudAnthropic agreed to pay Nscale up to $44.6B for GPU cloud capacity, if Nscale can finance and deliver it on time.Aug 2026 · CNBC
- $44BMicrosoft → NscaleBuys compute or cloudMicrosoft's contracts with Nscale, about $43.8B according to Nscale's IPO filing; Microsoft has now cancelled the part covering the 50 MW Loughton, Essex site (about 23,000 Nvidia GB300 GPUs). Microsoft ended its agreement to lease all 50 MW at Loughton because the site isn't expected to get grid power until after 2030. Nscale says its other Microsoft contracts aren't affected and it's looking for a new tenant and other power sources. No value was given for the cancelled part.Oct 2025 · changed · Reuters via Global Banking & Finance Review
- $40BGoogle → AnthropicInvestsGoogle agreed to invest up to $40B in Anthropic: $10B at a $380B valuation and up to $30B more on milestones, on top of more than $3B before.Apr 2026 · CNBC
- $40BApollo → SpaceXLends or financesReported $40B debt package to buy Nvidia AI chips: about $10B of bank loans and $30B of investment-grade debt. Apollo would lead and place the debt, with Pimco among lenders in talks. Expected to close in 2027. Talks reported by the FT; Bloomberg says they are preliminary and may not lead to a deal.Oct 2026 · in progress · Quartz (citing FT, Reuters, Bloomberg)
- $35BMeta → CoreWeaveBuys compute or cloudMeta agreed to buy $14.2B of CoreWeave AI cloud capacity in September 2025, then about $21B more through 2032.Sep 2025 · in progress · CNBC
- $33BAmazon → AnthropicInvestsAmazon invested $8B in Anthropic in 2023–24 and agreed in 2026 to put in up to $25B more, $20B of it tied to milestones. $13B invested so far.Nov 2024 · in progress · Amazon
- $30BNvidia → OpenAIInvestsNvidia bought $30B of OpenAI shares in its record 2026 round, which valued OpenAI at $852B. It replaced a September 2025 letter of intent to invest up to $100B, which was never finalised.Sep 2025 · changed · CNBC
- $30BMeta → NebiusBuys compute or cloudMeta signed a roughly $3B Nebius deal in November 2025, then up to $27B more over five years from 2027.Nov 2025 · in progress · Nebius
- $29BGoogle → SpaceXBuys compute or cloudGoogle will pay SpaceX $920M a month from October 2026 to June 2029 for about 110,000 Nvidia GPUs in xAI's data centres.Jun 2026 · CNBC
- $27BBlue Owl → MetaLends or financesBlue Owl funds put up most of about $27B to build Meta's Hyperion data centre in Louisiana, which Meta leases back, keeping the debt off its balance sheet.Oct 2025 · in progress · Meta
- $26BAMD, Broadcom, Google, Micron, Microsoft → AnthropicInvests$26.0B of non-voting Class N stock bought at the IPO price in a placement alongside Anthropic's IPO. It depends on the IPO closing. The prospectus split: about $10B each from Google and Nvidia, $2.5B from AMD, $1B each from Broadcom, Micron and Microsoft, and $500M from TSMC. This partly overlaps existing commitments. Google's $10B comes from fully using an investment option granted in March, which cuts what is left under that financing agreement from $20B to $10B. AMD's $2.5B is half of its $5B equity commitment.Nov 2026 · Dealroom News
- $25BBond investors → MicrosoftLends or finances$25B of senior unsecured notes in 10 tranches maturing from 2028 to 2066, run by Wells Fargo, JPMorgan and UBS; proceeds go to general corporate purposes including capex Microsoft's first US investment-grade bond sale since 2017; orders topped $100B. No amount is set aside specifically for AIOct 2026 · Reuters via Investing.com
- $22BOpenAI → CoreWeaveBuys compute or cloudOpenAI signed three CoreWeave GPU cloud contracts in 2025 worth up to $22.4B.Mar 2025 · in progress · CoreWeave
- $17BMicrosoft → NebiusBuys compute or cloudMicrosoft agreed to pay Nebius $17.4B (up to $19.4B) for GPU capacity in New Jersey through 2031.Sep 2025 · in progress · Bloomberg
- $11BSoftBank, MGX & other investors → OpenAIInvestsFirst close of about $11B in a funding round valuing OpenAI at $1.25T; the round could reach as much as $20B in the coming weeks Below the original target of up to $30B and the $1.4–1.5T valuation first sought. Investors named include Coatue, T. Rowe Price, SoftBank, MGX, Sequoia, Founders Fund and Andreessen Horowitz.Nov 2026 · in progress · Bloomberg
- $10BMeta → GoogleBuys compute or cloudMeta signed a six-year Google Cloud contract worth more than $10B, and in 2026 a further multibillion-dollar deal to rent Google's TPU chips.Aug 2025 · in progress · CNBC
- $10BOpenAI → CerebrasBuys compute or cloudOpenAI agreed to pay more than $10B for 750 MW of Cerebras inference compute through 2028.Jan 2026 · Bloomberg
- $10BNvidia → AnthropicInvestsNvidia committed to invest up to $10B in Anthropic in the three-way deal with Microsoft.Nov 2025 · in progress · Bloomberg
- $9.7BMicrosoft → IRENBuys compute or cloudFive-year GPU cloud contract worth about $9.7B for 200 MW at IREN's Horizon facilities in Childress, Texas Deliveries delayed by a network design change Microsoft requested. Under the contract, delivery dates are extended without delay credits. IREN's target of more than $4B in annualised revenue moves from year-end 2026 to January 2027, possibly February.Nov 2025 · changed · Reuters
- $6.3BNvidia → CoreWeaveBuys compute or cloudNvidia agreed to buy any CoreWeave capacity its customers don't use, up to $6.3B through 2032, and put $2B more into CoreWeave shares in January 2026.Sep 2025 · in progress · CNBC
- $5BMicrosoft → AnthropicInvestsMicrosoft committed to invest up to $5B in Anthropic as Anthropic signed its $30B Azure contract.Nov 2025 · in progress · Bloomberg
- $5BAMD → AnthropicInvests$5B equity commitment written into the July hardware supply framework Under the amended prospectus, $2.5B (half) will be paid through the IPO placement of Class N shares. The rest is available only as AMD chips are delivered and switched on.Jul 2026 · in progress · Scenarica
- $5BNvidia → IntelInvestsNvidia bought $5B of Intel shares (about 4%), and the two will develop data centre and PC chips together.Sep 2025 · Nvidia
- $5BJPMorgan & Goldman Sachs-led lenders → Volta InfrastructureLends or financesA $5B leveraged loan for Volta's Norway data centre campus run with Bitdeer, where Anthropic has a six-year compute agreement. It's split into a $1.3B underwritten term loan and a $3.7B chip loan, sold on a best-efforts basis, to buy about 36,000 Nvidia GPUs. Marketed at a rate of at least 11% and anchored by a $1.5B Apollo order; some lenders pushed back over exposure limits and Volta's reliance on Anthropic.Oct 2026 · Semafor
- $5BBlackstone Digital Infrastructure Trust → AmazonLends or financesSale-leaseback: BXDC buys 75.1% of two AWS joint ventures, valued at $5B, holding 13 new powered-shell data centres (647 MW) in northern Indiana and Mississippi. AWS keeps about 25% and leases back the whole portfolio. BXDC is paying with about $1.9B of IPO cash and about $2.5B of new non-recourse mNov 2026 · CASRAI
- $3.5BCiti → NebiusLends or finances$3.5B senior secured facility (364-day bridge loan at term SOFR + 2.75%, rising to at most 3.50%) for data centre development, GPU purchases and general corporate purposes Nebius says larger asset-backed loans against its more than $40B of investment-grade customer contracts may follow.Oct 2026 · Nebius
- $2.6BAramco → HumainInvestsA 49% stake in Saudi AI company Humain for about SAR 9.9B ($2.6B) in cash in 2026, plus AI, compute and digital assets; Humain plans 3 GW of AI data centre capacity by 2030 The PIF keeps the other 51%Nov 2026 · GamesBeat
- $2BNvidia → SpaceXInvestsNvidia invested in xAI's $20B raise, part of which buys Nvidia GPUs to lease to xAI; xAI became part of SpaceX in February 2026. Reported as up to $2B; later reports put Nvidia's stake higher.Oct 2025 · changed · Bloomberg
Who benefits
The build-out as a stack, from the apps people use down to the power stations. Each layer shows the companies on my watchlist there, with share prices over the past year.
Over the past year the market has paid most for memory and storage (a median +104%) and servers (+55%), and least for clouds and data centres (−39%).
Models and apps
The labs and the software built on them: where the money has to come back from.
−8%median, 1 yearClouds and data centres
The hyperscalers, the newer GPU clouds and the landlords who rent them space.
−39%median, 1 yearServers
The companies that assemble the racks.
+55%median, 1 yearNetworking and optics
Switches, cables and lasers that tie thousands of chips into one computer.
+40%median, 1 yearChips
GPUs, custom AI accelerators and the CPUs beside them.
Memory and storage
High-bandwidth memory stacked beside every AI chip, and the drives that feed it.
+104%median, 1 yearChipmaking
The foundries and the machines that make the chips.
+31%median, 1 yearCooling and electrical
Liquid cooling, switchgear and backup power inside the building.
+1%median, 1 yearPower and land
Electricity, grid gear, turbines and sites to build on. The slowest thing to add.
+6%median, 1 year
Worth watching
Companies the build-out runs through, many of them where it's short of something: power, memory, cooling, optics. Why each matters now, and what could go wrong. Not advice.
Bloom Energy
NYSE:BE · Power and land
+53% 1YOn 13 October 2026 Oracle confirmed that Bloom fuel cells will be the main power source for its Project Jupiter campus in New Mexico, supplying up to 2.45 GW.
Risk: The microgrid's air permit and the gas pipeline it relies on were both still waiting for approval, and Oracle has sent a force majeure notice that would let it defer rent if power isn't ready by 2028.
CapacityGE Vernova
NYSE:GEV · Power and land
+26% 1YThe shares fell 10.64% on 22 October 2026, the day after Meta's results showed negative free cash flow, and 28 October results will show whether gas turbine orders and output are holding up.
Risk: The stock fell with other AI stocks on worries about how data centres are funded, so slower data centre orders or a miss on the 20 GW yearly turbine output target could weigh on it further.
TIKRSiemens Energy
XETR:ENR · Power and land
+6% 1YOn 30 September 2026 Siemens Energy agreed to supply 119 SGT-400 gas turbine cores (about 1.7 GW) to Dynamis for mobile power packages aimed at US data centres, with deliveries from 2027.
Risk: About a fifth of its latest quarter's orders came from data centres, so the shares have moved with worries about how AI is funded, and its next results are due 11 November.
Interesting EngineeringConstellation Energy
NASDAQ:CEG · Power and land
−30% 1YIn early October 2026 Google signed a 20-year deal to buy 890 MW of new nuclear capacity from upgrades at Constellation reactors already running in Illinois, Pennsylvania and New Jersey. That came a week after its Amazon deal.
Risk: The income is contracted, but the extra megawatts still have to come from reactor upgrades, and any delay could hurt.
24/7 Wall St.Vistra
NYSE:VST · Power and land
−33% 1YOn 5 October 2026 the US Department of Energy offered a conditional commitment of up to $4.2B for Vistra to add 433 MW of output at its Beaver Valley, Davis-Besse and Perry nuclear plants.
Risk: It is a conditional loan commitment, not a loan, and the work is likely to come after 2028.
William David (Substack)Vertiv
NYSE:VRT · Cooling and electrical
+4% 1YJune-quarter sales up 24% to $3.27B, and 2026 guidance raised to $13.8–14.2B on demand for liquid cooling and power gear for AI.
Risk: An expensive share price and a few big buyers mean any pause in GPU deployments shows up in orders fast.
SEC filingSchneider Electric
EURONEXT:SU · Cooling and electrical
+1% 1YRecord first-half revenue of €21.2B, with June-quarter growth of 17% (23% in North America) and data centre demand 'at a very high level'.
Risk: Data centres are only part of a broad industrial business, so a European slowdown can offset the AI boost.
tED magazineEaton
NYSE:ETN · Cooling and electrical
−4% 1YRecord June quarter: sales up 21% and its electrical backlog more than doubled in a year.
Risk: The share price already reflects the data centre cycle, and switchgear lead times could shorten as rivals add capacity.
Pulse 2.0Tokyo Electron
TSE:8035 · Chipmaking
+40% 1YJune-quarter sales up 33% and operating income up 46%, with a record first-half forecast on AI server, logic and memory demand.
Risk: Heavy exposure to China and memory makers' spending, plus swings in the yen.
QuartrLam Research
NASDAQ:LRCX · Chipmaking
+32% 1YRecord $6.72B quarter in July 2026, guiding to $8.1B, and it raised its view of 2026 chip equipment spending to the low $150Bs.
Risk: Nearly half its sales are to memory makers, and China export rules could tighten.
TIKRAdvantest
TSE:6857 · Chipmaking
+30% 1YJune-quarter sales up 39% and operating income up 53%, from testers for AI chips and HBM memory.
Risk: Tied to a few AI chip programmes, so a slowdown in GPU and HBM volumes hits quickly.
AdvantestKLA
NASDAQ:KLAC · Chipmaking
+15% 1YRecord $3.66B quarter; its inspection tools for advanced chip packaging are up more than 70%, heading for about $1.1B this year.
Risk: China exposure, and a downturn in chip equipment spending would squeeze its premium valuation.
FinvizSK hynix
KRX:000660 · Memory and storage
+108% 1YSK hynix fell 10.09% in Seoul on 13 October 2026 after China's CXMT said it expects to launch denser 4F² server memory by the end of the year.
Risk: CXMT's share of the global DRAM market has risen to about 10%, which could add supply and push down memory prices over time, although analysts say it still has trouble with HBM yields.
Technology.orgSamsung Electronics
KRX:005930 · Memory and storage
+101% 1YOn 8 October 2026 Samsung guided to a record September-quarter operating profit of about 107.4 trillion won (roughly US$80B). That is up about 783% on a year earlier, on revenue of about 195 trillion won, as AI memory demand and higher prices lifted its chip business.
Risk: The shares fell after the result. Revenue came in below some analyst estimates, and the stock was about 25% below its June high, which suggests the memory upcycle may already be in the price.
CNBCLumentum
NASDAQ:LITE · Networking and optics
+100% 1YRevenue more than doubled to $1.01B in its June quarter, and it guided higher again on demand for the lasers in AI optical links.
Risk: Optics has always been cyclical and prone to inventory gluts, and converting its notes to shares diluted shareholders.
SEC filingMarvell Technology
NASDAQ:MRVL · Networking and optics
+60% 1YData centre revenue up 46% to $2.17B in its August quarter; it now expects about $18B of revenue in its 2028 fiscal year as custom AI chips ramp.
Risk: Custom chip revenue rests on a few hyperscaler programmes that can be lost to Broadcom or in-house teams.
FuturumArista Networks
NYSE:ANET · Networking and optics
+40% 1YArista fell 18.34% in the five sessions after its 9 October 2026 record close, without missing a forecast or cutting guidance, which makes its 3 November results a test of AI networking demand.
Risk: Its gross margin slipped to 63.4% from 65.6% a year earlier, and a pause in AI spending is the main threat.
TIKRCorning
NYSE:GLW · Networking and optics
+22% 1YOptical sales up 32% in the June quarter, a multibillion-dollar fibre deal with Amazon, and a pact with Nvidia to make ten times more optical connectors in the US.
Risk: It missed guidance in July, and display glass still dilutes the AI story.
Business WireCredo Technology
NASDAQ:CRDO · Networking and optics
−25% 1YRevenue up 115% to $479M in its July quarter, with growth guidance for the year raised to 85%, on the copper cables that link AI racks.
Risk: A handful of customers, and short copper links could be replaced by optics.
SEC filingDell Technologies
NYSE:DELL · Servers
+138% 1YBarclays downgraded Dell on 14 October 2026, arguing that its strong enterprise sales reflect higher memory costs more than real enterprise AI adoption, and the shares fell 11% that day.
Risk: The shares had risen more than 300% this year, so any sign that business AI spending is arriving later than expected could hit them hard.
CNBCCelestica
NYSE:CLS · Servers
−29% 1YJune-quarter revenue up 62%, 2026 guidance raised to $20.5B, and it expects growth to speed up in 2027.
Risk: A contract manufacturer that depends on a few hyperscalers' custom AI and networking programmes.
SEC filingEquinix
NASDAQ:EQIX · Clouds and data centres
+32% 1YJune-quarter revenue up 16%, a record number of new connections, and a higher growth outlook to 2029 with Nvidia and Cisco partnerships.
Risk: Grows more slowly than pure AI landlords, and rising capex and interest rates weigh on returns.
SEC filingAkamai Technologies
NASDAQ:AKAM · Clouds and data centres
−2% 1YOn 24 September 2026 Akamai signed an $11.6B, seven-year deal to supply Anthropic with CPU computing, its largest contract ever, with room to grow to about $20B. This makes it a new supplier of the general-purpose computing that runs around AI models.
Risk: It plans about $5.5B of capex for the deal, more than six times its total 2025 spending, mostly before revenue arrives. It also gave Anthropic a warrant for up to about 5% of its shares.
Akamai press release (GlobeNewswire)Goodman Group
ASX:GMG · Clouds and data centres
−6% 1YOperating profit up 15.7% to A$2.67B for the year to June, with data centres now 78% of its A$19.7B of work in progress.
Risk: Shares are down about 20% in a year on doubts its powered land will turn into signed hyperscale tenants.
Motley FoolNEXTDC
ASX:NXT · Clouds and data centres
−35% 1YSigned a record 250 MW commitment at its S4 Sydney campus, lifting contracted capacity 60% to 667 MW, with A$8.4B of funding in place.
Risk: Building it has meant new shares and debt, and the revenue only starts once power and fit-out are delivered.
NEXTDCCoreWeave
NASDAQ:CRWV · Clouds and data centres
−43% 1YCoreWeave hit a 52-week low of $53.50 on 22 October 2026. It had about 1.85 GW of capacity at the end of June against 4.2 GW of contracted backlog, so it still has to fund a big build-out.
Risk: Interest costs are rising quickly and debt is about 8.9 times equity, so tighter credit markets could threaten its expansion.
The Motley FoolApplied Digital
NASDAQ:APLD · Clouds and data centres
−46% 1YRevenue in the quarter to August rose 322% to $341.9M (reported 7 October 2026). It also signed a new 210 MW, 15-year lease with an investment-grade hyperscaler, worth about $5.2B over the base term.
Risk: Net loss widened to $221.0M, from $18.5M a year earlier, and long-term debt rose to about $6.3B as construction continues.
Applied Digital 8-K (SEC)Oracle
NYSE:ORCL · Clouds and data centres
−51% 1YIn the week of 13 October 2026 Oracle proposed a power agreement with El Paso Electric and a change to the Project Jupiter microgrid that would cut its projected emissions by about 35%; a further update on the project is due on 28 October.
Risk: It has been downgraded to BBB-, one notch above junk, and S&P Global Market Intelligence data show $37.1B of cash, a cash burn of nearly $29B a year and $169.1B of debt, while OpenAI doesn't have to pay for the site before 2027.
The Motley FoolCipher Digital
NASDAQ:CIFR · Clouds and data centres
−62% 1YOn 25 September 2026 the former bitcoin miner extended its Barber Lake (Texas) data centre leases from 10 to 20 years, with Fluidstack and an unnamed AI lab. That lifts contracted revenue at the site from $3.8B to more than $9B.
Risk: Delivery of the data halls has slipped to between the December 2026 and March 2027 quarters. Cipher also bears the first $359.3M of any cost overruns.
DatacenterDynamicsPalantir
NASDAQ:PLTR · Models and apps
−8% 1YJune-quarter revenue up 93% and US commercial revenue up 149%: a sign businesses are paying for AI software, not just trying it.
Risk: Its valuation is extreme against its revenue, and government contracts make results lumpy.
SEC filing
How fast it's growing
The compute that trains the biggest models, the tokens they get through, and the electricity behind them, year by year. The big number is the growth rate the points so far fit best (the dashed grey line). Compute and tokens are on a log scale, where every gridline is ten times the one below, so steady growth is a straight line. Hollow points are projections. Hover a point for its source.
Compute to train the biggest models
4× a yeardoubling every 6 months
The biggest language models each year, by the calculations it took to train them; most are Epoch AI’s estimates. From 3.1 × 10²³ in May 2020 to 1 × 10²⁷ FLOP in Sep 2026. Epoch AI: 5× a year since 2020
AI chips shipped (Nvidia)
3× a yeardoubling every 8 months
The computing power of every Nvidia AI chip shipped since 2022, in H100s’ worth. Nothing is counted as retired. From 1.4 million in Dec 2023 to 21 million H100-equivalents in Jun 2026. Epoch AI: all AI chips, 3.4× a year
Tokens Google processes a month
19× a yeardoubling every 3 months
Across all its products: Search, Gemini, Workspace, the cloud. A token is about three-quarters of a word. From 9.7 trillion in May 2024 to 3.2 quadrillion tokens in May 2026. Google: more than 300 times in two years
Tokens through Google’s AI API a minute
5.3× a yeardoubling every 5 months
Customers calling Google’s models directly: businesses and developers building on them, paying by the token. From 7 billion in Oct 2025 to 22 billion tokens a minute in Jul 2026.
US data centre electricity
+14% a yeardoubling every 5.3 years
A year, all data centres, not just AI. The hollow points are LBNL’s reference case, with its range of scenarios. From 60 in 2014 to 192 TWh in 2024. LBNL: +21% a year, 2026 to 2030 (projected)
World data centre electricity
+17% a yeardoubling every 4.4 years
A year, all data centres. Only two years are measured on the same basis so far, so the fitted rate is rough. From 415 in 2024 to 485 TWh in 2025. IEA: about 12% a year since 2017
The power problem
Electricity used by data centres, in terawatt-hours a year. Hatched bars are projections; the whiskers show the range between scenarios. Chips can be bought in months; power stations and grid connections take years.
The world
United States
Will it pay off?
The strongest facts on each side, refreshed every week.
The case it pays off
- ASML reported record September-quarter sales of €11.7B and said it now expects its planned supply for 2027 and 2028 will not fully meet customer demand, with some customers interested in ordering for 2029 and 2030. ASML, 14 Oct
- Lam Research reported record September-quarter revenue of $8.22B, up 54% on a year earlier, with record gross and operating margins on AI-related chip equipment demand. Lam Research, 21 Oct
- Supermicro estimated its September-quarter revenue at $18.5–19.5B, about $4B above the middle of its own guidance, mainly on demand for AI platforms (preliminary and unaudited). Supermicro, 20 Oct
- Meta's September-quarter revenue rose 26% to $64.6B, with average ad prices up 14%, and it forecast $73–76B of revenue for the December quarter. Meta, 21 Oct
The case it doesn’t
- Gartner estimated that AI data centre owners would need $8.5 trillion of revenue through 2030 to cover planned spending, financing and a 12% return, but forecast no more than $3.6 trillion, leaving over $3.5 trillion of spending exposed to write-downs. Gartner, 14 Oct
- Meta's September-quarter capital spending of $34.91B was more than its $32.79B of operating cash flow, leaving free cash flow at negative $2.12B. Vested Finance, 21 Oct
- About $37B of the roughly $80B of data centre bonds issued in 2026 is rated junk, more than four times the 2025 level, according to an analysis of FactSet data. BigGo Finance, 21 Oct
- Chip stocks fell after a Financial Times report put OpenAI's annualised revenue $20B below earlier estimates, with the Philadelphia Semiconductor Index down as much as 4% during the session. TIKR, 8 Oct
- CoreWeave's five-year credit default swap hit a record intraday 1,194.5 basis points as lenders grew worried about AI data centre debt. The SaaS Library (citing Reuters), 15 Oct
Lately
The biggest developments, newest first.
16 Nov 2026
The US Commerce Department's BIS issued an interim rule requiring a licence to ship advanced AI chips to any data centre worldwide that gives companies headquartered in China, Macau or other D:5 countries more than 12 million TPP of compute, and adding licence requirements for ex Unite.AI
16 Nov 2026
Blackstone Digital Infrastructure Trust agreed to buy 75.1% of two AWS joint ventures, valued at $5B, holding 13 new powered-shell data centres (647 MW) in northern Indiana and Mississippi; AWS keeps the rest and leases back the whole portfolio. CASRAI
16 Nov 2026
TensorWave signed a six-year deal to supply OpenAI with 457 MW of dedicated capacity on AMD Instinct MI455X GPUs and Helios racks across several US sites, with first capacity in the first half of 2027 and the full deployment by early 2028; no dollar value was disclosed. Unite.AI
12 Nov 2026
Jensen Huang resigned as Nvidia's president, CEO and director with immediate effect, five days before Nvidia's Nov 17 results; CFO Colette Kress is interim CEO while keeping the CFO job, and former Synopsys CEO Harvey Jones became Nvidia's first board chair. Nvidia Newsroom
12 Nov 2026
Nebius's Q3 revenue rose 571% to $980.8M, but it now expects 2026 revenue at the low end of its $3.0–3.4B range after delays at a New Jersey colocation site; it raised 2026 capex to about $27B and guided 2027 revenue of $12–13B on $40–45B of capex. Panabee
12 Nov 2026
Naver signed a KRW 2 trillion (about $1.5B) AI computing services contract with an unnamed US AI inference company, the first major customer for its AI Factory business. DIGITIMES
10 Nov 2026
Anthropic's amended S-1 sets an IPO of 825 million shares at $70–78 (up to about $64.35B) to list on Nasdaq as ANT, plus a $26B non-voting placement to AMD, Broadcom, Google, Micron, Microsoft, Nvidia and TSMC; it also discloses about $900B of compute and infrastructure commitmen Dealroom News
10 Nov 2026
CoreWeave's Q3 revenue rose 168% to $3.66B and its backlog reached $132.5B, but its net loss widened to $709M; it raised 2026 capex guidance to $37–39B and expects Q4 interest expense of $1.05–1.15B. Unite.AI
8 Nov 2026
The FT reports Anthropic agreed to pay about $3.4B for 1.7 GW of gas-fired generators for its data centres by taking over OnePWR Solutions' Caterpillar generator orders, which the FT called the largest known purchase of power equipment by an AI lab. Bloomberg
6 Nov 2026
Microsoft is winding down its 2023 deal to rent AI computing from Oracle for Bing after deciding not to renew it, because the older Nvidia hardware no longer met its needs; Bloomberg called it part of a wider review of Microsoft's more than $80B of rented outside capacity. Reuters
5 Nov 2026
The day after Democrats swept the US midterms, the Philadelphia Semiconductor Index fell 12.25% to 9,011.14 with all 30 members down, its worst day since March 2020; Micron fell 17.46%, SanDisk 22.26% and Nvidia about 9%, on fears that data centre building will slow. TradingKey
5 Nov 2026
Microsoft will not take up its option to more than double its Texas contract with Nscale, an extra 700 MW the FT said was worth tens of billions of dollars; a source said Nscale's roughly $103B total contract value is unchanged. Reuters
5 Nov 2026
IREN said a network design change Microsoft asked for has delayed some of the 200 MW it is building for Microsoft in Texas, pushing its target of more than $4B in annualised revenue from year-end to January, possibly late February; it also plans about $15B of capex for the rest o Reuters
4 Nov 2026
Google will invest $15B in Malaysia in 2027–28 to expand its Elmina campus in Selangor and build new campuses in Selangor and Negeri Sembilan, adding to the $2B it announced in 2024. Malay Mail
30 Oct 2026
Nvidia is in talks to guarantee billions of dollars of debt for Nscale's West Virginia campus, where Anthropic has a $44.6B contract for the first 460 MW building and the two companies are discussing a second deal of about $45B. TechCrunch
29 Oct 2026
AWS revenue rose 39% to $45.98B while Amazon's trailing-12-month free cash flow turned to an outflow of $42.4B; Amazon held its 2026 capex at about $220B, said it will spend meaningfully more in 2027 and will sell Trainium chips outside AWS from late 2027. CNBC
29 Oct 2026
Microsoft raised about $25B in its first US investment-grade bond sale since 2017, drawing more than $100B of orders, a day after its CFO said it would look for outside funding for the AI build-out. Reuters via Investing.com
28 Oct 2026
Microsoft's Azure grew 48% in the September quarter, and capex including finance leases was $45.2B against the $50.67B analysts expected; it cut its calendar-2026 capex forecast to about $170B because deliveries from third-party GPU cloud providers have slipped. CNBC
28 Oct 2026
Google Cloud revenue rose 103% to $30.7B, helped by sales of TPU systems, and its backlog reached $561B; Alphabet spent $51.4B on capex, its free cash flow was negative $9.1B, it kept its 2026 capex guidance at $195–205B and said capex will rise significantly in 2027. AlphaSense
28 Oct 2026
SK hynix posted record third-quarter revenue of 104.6 trillion won with an 80% operating margin, said HBM4 will be its main HBM product from the fourth quarter, and has long-term deals covering more than half of its 2027–28 capacity. SK hynix Newsroom
27 Oct 2026
OpenAI reportedly plans to buy Google's TPU chips, with no terms disclosed and neither company confirming, while Oracle said it will offer Google TPUs on its cloud from 2027 in a multi-year, multi-gigawatt partnership. TrendForce
26 Oct 2026
Anthropic's IPO prospectus puts its future compute and infrastructure commitments at $542–567B, including up to $120.5B with SpaceX's AI unit through 2029, and launches 'Anthropic Direct', its plan to lease dedicated data centres from partners with $125.2B of rent over five years Fortune
22 Oct 2026
The Philadelphia Semiconductor Index fell 6.72% to 10,731.98, with all 30 members down and about $200B of market value lost, after Lam's supply warning. Concern over Meta's roughly $825B of spending commitments also weighed, and the Nasdaq fell 2.6%. Tech Times
22 Oct 2026
Nebius took a $3.5B senior secured facility from Citi for data centre development and GPU purchases. The loan matures in 364 days and carries an initial rate of term SOFR plus 2.75%. Nebius
22 Oct 2026
At GTC Berlin, Nvidia CEO Jensen Huang said neocloud demand is 'off the charts' but capital is scarce, and that Nvidia is trying to get lenders to treat its chips as a financeable asset. Nvidia's stock was down 7.6% for October by that Friday. CNBC
21 Oct 2026
Meta's third-quarter capex rose to $34.9B, above its $32.8B operating cash flow, so free cash flow was negative $2.12B. It narrowed its 2026 capex guidance to $135–145B (from $130–145B) and gave no 2027 figure. Fortune
21 Oct 2026
Lam Research posted record quarterly revenue of $8.22B, up 54%, and its first operating margin above 40%. It guided December-quarter revenue to $8.6B ± $0.4B and said supply-chain constraints held that guidance back; the shares fell about 9% the next morning. 24/7 Wall St.
21 Oct 2026
Nvidia and German energy firm PreussenElektra agreed a preliminary partnership to study turning decommissioned German nuclear power plant sites into AI data centres; the plan does not involve using nuclear power. Tom's Hardware
20 Oct 2026
SpaceX's third-quarter revenue rose 161% to $14.58B, ahead of the $12.72B estimate. AI revenue grew more than ninefold to $7.6B, mostly from renting compute to developers including Anthropic, Google and Reflection AI, and AI took $16.4B of its $19.6B capital spending. NBC News (Reuters)
20 Oct 2026
Three shut-down US nuclear reactors are being restarted to meet AI data centre power demand, with backing from Microsoft and Google, and are expected to add 2.25 GW to the grid. Tom's Hardware
18 Oct 2026
Microsoft has pulled out of its deal to lease all 50 MW at Nscale's planned Loughton, Essex data centre, which was meant to hold about 23,000 Nvidia GB300 chips, after the site turned out to be unlikely to get grid power until after 2030; Nscale says its other Microsoft contracts KuCoin News (citing The Telegraph/Reuters)
16 Oct 2026
Taiwan plans to add AI servers and cutting-edge chips to its export control list, which would make shipping restricted AI hardware to China a criminal offence under its Foreign Trade Act, as part of its trade deal with the US; no start date has been set. Bloomberg
15 Oct 2026
TSMC's third-quarter net profit rose 68.7% to a record NT$763.1B on revenue of NT$1.49 trillion, beating estimates, and it guided fourth-quarter revenue to $52.3–54.3B. CNBC
15 Oct 2026
CoreWeave's shares and bonds kept falling after a more than 15% one-day drop: it carries about $50B of debt, yields on its 2031 bonds topped 16%, and the cost of insuring its debt against default reached about 1,000 basis points. Reuters via U.S. News
14 Oct 2026
ASML posted record third-quarter sales of €11.7B and €5.0B of net income, said its planned supply for 2027 and 2028 won't fully meet customer demand, and narrowed its 2026 sales forecast to €44–45B. Quartz
13 Oct 2026
Blackstone-backed AirTrunk postponed its roughly $1.5B Singapore data centre REIT IPO, which would have valued the REIT at about $15B, to early 2027 amid the tech and AI stock sell-off. Reuters via The Edge/i3investor
13 Oct 2026
JPMorgan and Goldman Sachs marketed a $5B debt deal for neocloud Volta's Norway data centre, where Anthropic is the main compute buyer, at a rate of at least 11%, anchored by a $1.5B Apollo order, after some lenders said they were full on data centre debt. Semafor
13 Oct 2026
Kentucky's Mason County approved a hyperscale data centre deal with Meta, with about $15B of initial investment under a 40-year multi-phase plan that could reach up to $800B. WKYT
10 Oct 2026
Nvidia is in early talks to deepen its $800M investment in open-weight model maker Reflection AI, last valued at $25B, or to acquire it, possibly as an acqui-hire, the FT reported. Reuters via U.S. News
9 Oct 2026
Nvidia-backed Australian data centre operator Firmus pulled its planned $5B ASX IPO, which would have valued it at about $30.6B (nearly triple its August valuation), and will raise money privately instead. CNBC
Sources and method
Capex and revenue are from each company's results, by calendar quarter (Microsoft's and Oracle's fiscal quarters are put in the calendar quarter they mostly cover). They're not quite like for like: each company reports capex its own way, as noted under the chart. The split of where the money goes is a rough estimate from the analysts below, not reported figures. Every week an AI model (anthropic/claude-opus-5.5) with web search checks for new results, guidance, deals and news, and refreshes the watchlist and the case each way; anything without a source that loads is thrown out. It can still be wrong, so check the links. Share prices from Yahoo Finance, updated 20 Nov 2026. Nothing here is financial advice.
All 45 sources
- Microsoft investor relations: earnings
- Alphabet 10-Q and 10-K filings (SEC)
- Amazon 10-Q and 10-K filings (SEC)
- Meta 10-Q and 10-K filings (SEC)
- Oracle 10-Q and 10-K filings (SEC)
- Microsoft: Calendar 2026 guidance
- Alphabet: 2026 guidance
- Amazon: 2026 guidance
- Meta: Full-year 2026 guidance
- Oracle: FY2027 (Jun 2026 – May 2027) guidance
- Nvidia CFO commentary, FY2026 Q3
- Nvidia CFO commentary, FY2027 Q1
- Nvidia CFO commentary, FY2027 Q2
- 404K Research: Combined full-year 2026 capex guidance from Meta, Alphabet, Amazon and Microsoft
- Bank of America: Big Tech capex forecast, 2026 and 2027 (raised)
- Wall Street consensus as cited by Goldman Sachs (via Yield Theory): 2027 capex for the five largest US hyperscalers, including Oracle
- Goldman Sachs (team led by Ryan Hammond): Combined AI-related capex of the five biggest US hyperscalers (Amazon, Alphabet, Microsoft, Oracle, Meta), 2027, compared with a widely cited US$1.1 trillion consensus
- Bernstein: the cost of a 1 GW Vera Rubin site (via Anue)
- McKinsey: The cost of compute, a $7 trillion race to scale data centers
- Morgan Stanley: Bridging a $1.5tr data center financing gap
- IEA: global data centre electricity
- IEA: global data centre electricity
- LBNL: US data centre electricity
- LBNL: US data centre electricity
- Compute to train the biggest models: Epoch AI
- Compute to train the biggest models: Epoch AI
- AI chips shipped (Nvidia): Epoch AI
- Tokens Google processes a month: Google I/O 2025
- Tokens Google processes a month: Alphabet Q2 2025 results
- Tokens Google processes a month: Google
- Tokens Google processes a month: Google I/O 2026
- Tokens Google processes a month: Google
- Tokens through Google’s AI API a minute: Alphabet Q3 2025 results
- Tokens through Google’s AI API a minute: Alphabet Q4 2025 results
- Tokens through Google’s AI API a minute: Alphabet Q1 2026 results
- Tokens through Google’s AI API a minute: Alphabet Q2 2026 results
- US data centre electricity: LBNL for the US DOE (2024)
- US data centre electricity: LBNL, 2025 update (2026)
- World data centre electricity: IEA, Energy and AI (2025)
- Interstate Highway System (35 years): About $114B at the time, in 2024 dollars
- Oil and gas exploration and production worldwide, one year: Global upstream oil and gas investment in 2025
- Apollo program (1960–73): $25.8B at the time, in 2025 dollars, by NASA's index
- Marshall Plan (1948–52): $13.3B at the time, in 2025 dollars
- International Space Station: ESA's estimate of €100B for building it and ten years of running it, not adjusted for inflation
- Manhattan Project: Nearly $2B at the time, in 2024 dollars
Share this page
The card is what people see on X.